One subscription. Four operating companies we already run. Capital is deployed into Irivon's own platform businesses and compounded through marketing, revenue growth, operations and technology — then returned through distributions and exits.
Irivon Capital Partners I is a pooled fund. Investors subscribe once; the manager selects and manages investments under the fund's mandate. Investors do not choose individual companies. The mandate is specific: capital is deployed only into Irivon's four operating platform companies — businesses Irivon founded or holds an economic interest in and runs day to day — to accelerate their revenue, systems and enterprise value.
An acquisition marketplace connecting business owners, buyers and intermediaries. 600+ business listings and a 20,000+ U.S. intermediary database.
Fund capital use: product, marketing, transaction services. exittobuy.comAI-native capital intelligence and decision infrastructure — an independent platform with its own users and roadmap.
Fund capital use: engineering, data, go-to-market. markettruth.aiAn AI platform that turns company knowledge into scalable training and operational content — onboarding, SOPs, organisational knowledge.
Fund capital use: product, sales, enterprise deployment. contentbuilder.aiA business-financing marketplace connecting companies with funding providers across loans, equity and acquisition finance.
Fund capital use: network growth, lender onboarding, marketing. apexbridge.coMost funds buy companies they have never run and hope management executes. Fund I deploys capital into four businesses Irivon built and operates — where the diagnosis is already done, the operating plan already exists, and the people executing it are the fund's own managers.
The portfolio is defined on day one — ExitToBuy, MarketTruth, ContentBuilder and Apex Bridge. Each has live users, revenue activity and a documented growth plan. The fund's job is acceleration, not discovery.
Capital is deployed as growth funding into companies Irivon controls or holds an interest in, on terms and valuations set out in the PPM — not through competitive auctions for third-party businesses at market multiples.
Irivon's partners run these companies. Marketing, revenue, operations and technology decisions are made by the same people who manage the fund, with quarterly reporting to investors on each company's plan and metrics.
Each company is a standalone asset with its own buyers: strategic acquisition, recapitalisation, secondary sale or continued ownership with distributions. Four companies mean four independent realisation paths within one fund.
Fund I is Irivon's first pooled fund. We distinguish clearly between the operators' experience, the platform companies' current traction and realised fund performance — of which there is none yet.
Businesses built, scaled and exited across the United States, Europe and the UAE; fifteen years of exit-preparation work for owners. Described on About.
All four companies are live and operating with external users. Traction figures are current operating metrics, not investment returns, and are updated in the fund materials.
Fund I has not made or realised any investments. No fund-level returns exist. Growth in a company's valuation is not a realised investor return until proceeds are distributed.
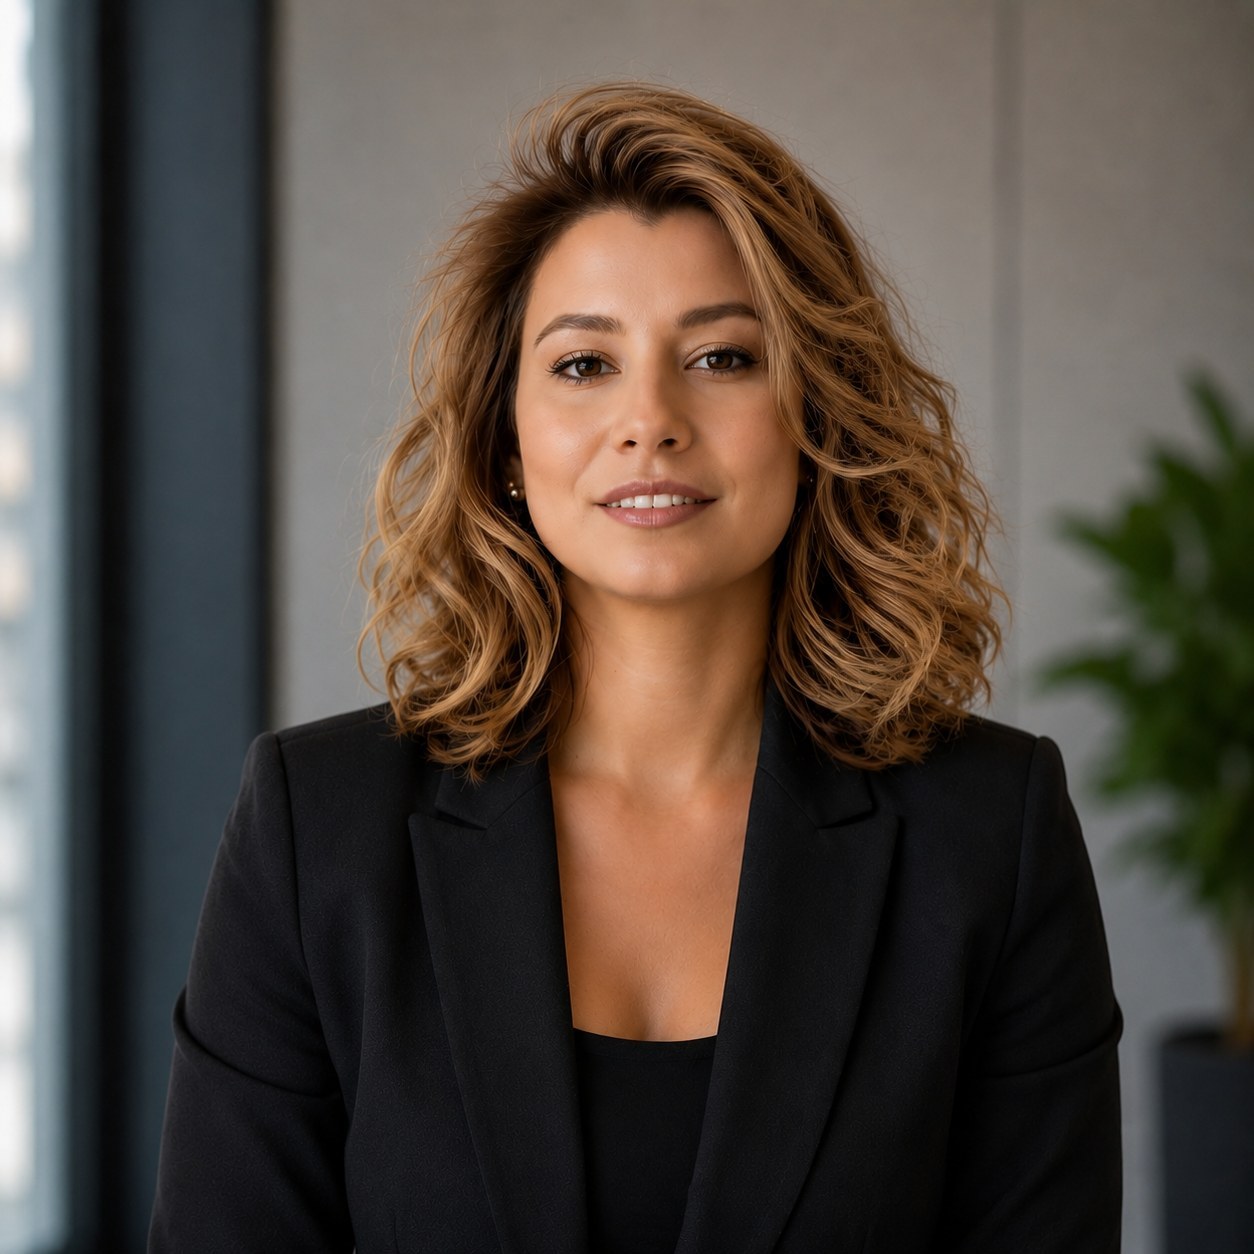
Marketing background; more than fifteen years increasing the value of businesses before their owners sold them, across the U.S., Europe and the UAE. Leads investment strategy, value-creation plans and operating systems. Founder of Irivon Capital, ExitToBuy and Apex Bridge.
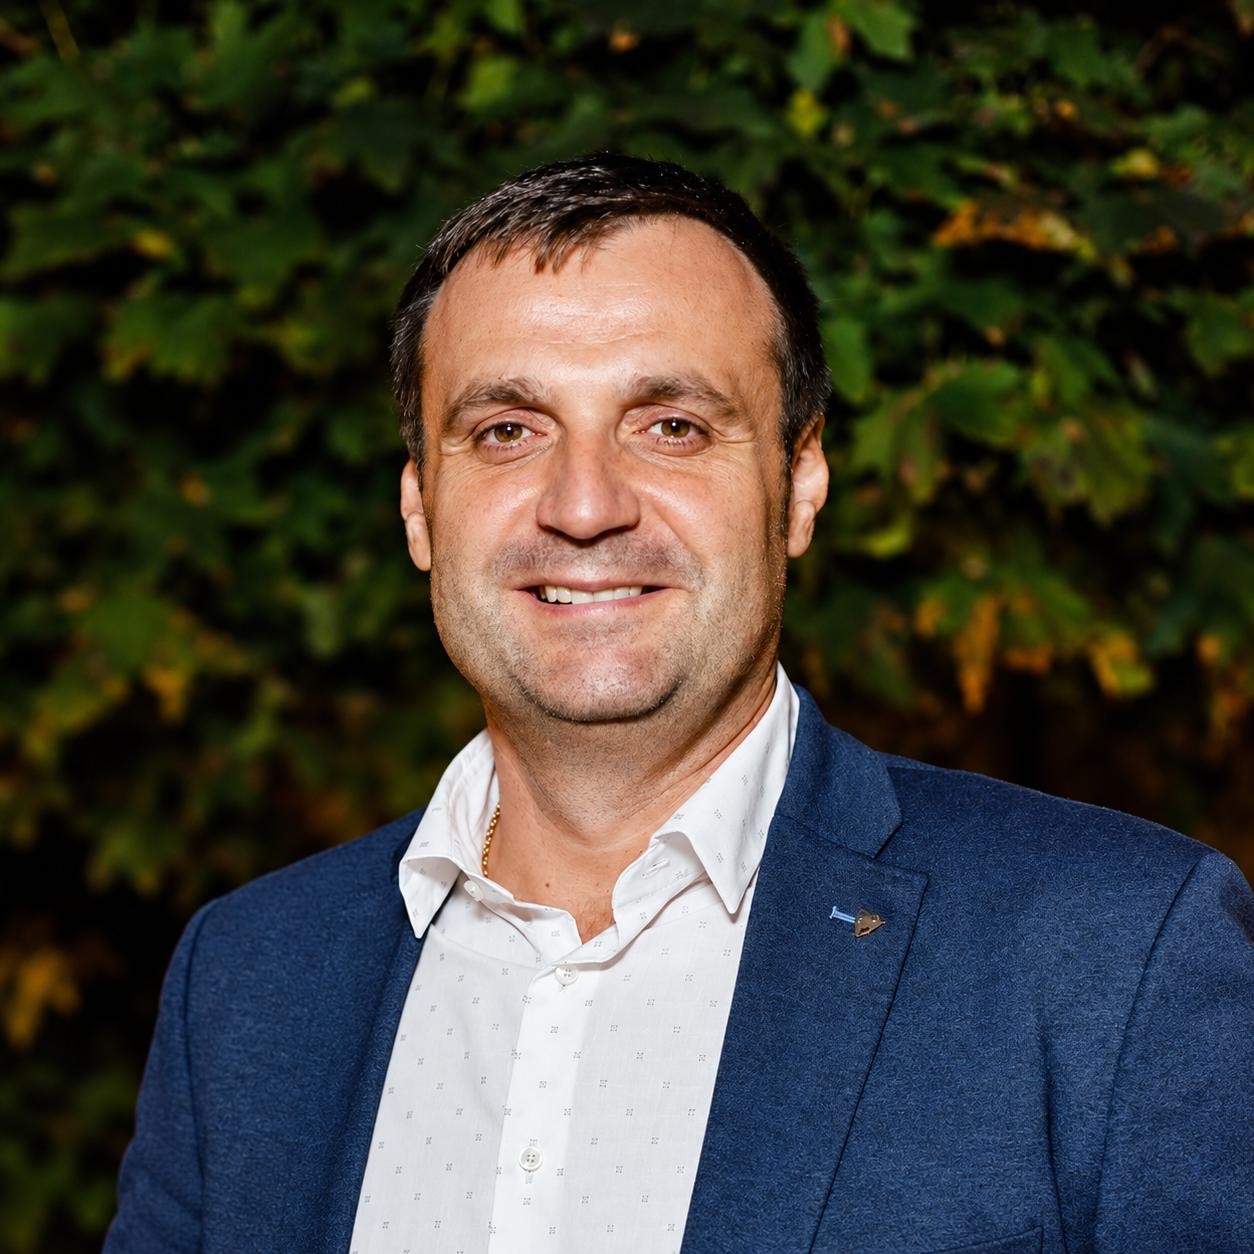
Entrepreneur and company builder with over 20 years in technology platforms, enterprise software, e-commerce and traditional industries. Founder of SmartExpert, the company behind ContentBuilder.ai; leads applied AI, product strategy and partnerships.
| Fund | Irivon Capital Partners I, LP |
|---|---|
| Manager | Irivon Capital Management LLC |
| Target fund size | $50,000,000 |
| Minimum investment | $250,000 |
| Investment mandate | Growth capital into Irivon's four operating platform companies — ExitToBuy, MarketTruth, ContentBuilder, Apex Bridge — and follow-on investment in the same companies only |
| Geography | United States (companies headquartered in the U.S.; customers and investors global) |
| Target portfolio size | Four companies |
| Target investment horizon | 5–7 years |
| Fund term & extensions | To be confirmed in PPM |
| Target net IRR | 28% |
| Target net equity multiple | ~4.4x at a 6-year realisation (3.4x at 5 years · 5.6x at 7 years) |
| Preferred return | To be confirmed in PPM |
| LP / GP profit split & carried interest | To be confirmed in PPM |
| Management fee | 2% annually on assets under management (AUM) |
| Other fees & expenses | Fund organisational and operating expenses as set out in the PPM Details to be confirmed |
| Distribution policy | Distributions at realisation events (exit, recapitalisation or sale of a portfolio company); no scheduled interim distributions |
| Investor eligibility | Accredited investors; U.S. and international, subject to applicable securities laws and jurisdictional requirements |
All terms are indicative until the Private Placement Memorandum and Limited Partnership Agreement are issued; those documents govern in the event of any inconsistency with this page.
Charged by Irivon Capital Management LLC on the fund's assets under management, calculated and billed as defined in the PPM. The fee funds the manager's investment and operating work across the four companies.
In addition to the management fee, the General Partner receives a share of profits (carried interest) under the LP/GP split set out in the PPM — on profits only, after investors' capital has been returned.
The fund invests in companies founded, owned or operated by Irivon's principals. This is the strategy, and it is a conflict of interest. Valuation methodology, approval and disclosure of each related-party investment are set out in the PPM.
Target returns are stated net — after the management fee, fund expenses and carried interest — unless otherwise indicated.
The fund's work follows the same arc as every value-creation engagement Irivon has run: put capital where the plan already exists, execute, and sell or distribute when the company is worth materially more.
A limited partner's journey has three steps. Nothing on this page secures an allocation; only a completed subscription accepted by the General Partner does.
A hypothetical illustration of the minimum commitment if Fund I achieved its 28% target net IRR with a single realisation at the end of year 6 and no interim distributions. It is not a forecast of actual performance.
Assumptions. Full $250,000 contribution at subscription (year 0); no interim distributions; one realisation event at the end of year 6 returning capital plus profit; 28% net IRR compounded annually (1.28⁶ = 4.40x). Figures are net of the 2% management fee, fund expenses and carried interest by construction — the gross return required to deliver this net outcome depends on the preferred return and LP/GP split to be set in the PPM. If capital is called in instalments, or realisations occur across years 5–7, timing and amounts change. Returned principal ($250,000) is shown separately from profit ($849,512) and exit proceeds are counted once.
| Year | Contribution | Distribution | Of which capital | Of which profit |
|---|---|---|---|---|
| 0 · Subscription | ($250,000) | — | — | — |
| 1 | — | $0 | — | — |
| 2 | — | $0 | — | — |
| 3 | — | $0 | — | — |
| 4 | — | $0 | — | — |
| 5 | — | $0 | — | — |
| 6 · Realisation | — | $1,099,512 | $250,000 | $849,512 |
| Total | ($250,000) | $1,099,512 | $250,000 | $849,512 |
Tell us who you are and we will send the fund overview, arrange a private conversation with the General Partners and, for eligible investors, provide the PPM and subscription documents.
The fund and the manager. Irivon Capital Partners I, LP (the "Fund") is a private pooled investment fund managed by Irivon Capital Management LLC (the "Manager"). Irivon Capital is the operating brand of the Manager and its affiliates.
No offer. This page is for informational purposes only and does not constitute an offer to sell or a solicitation of an offer to buy interests in the Fund. Any offer will be made only to eligible investors by means of a confidential Private Placement Memorandum and definitive fund documents, which contain important information about objectives, strategy, risks, fees, expenses, conflicts of interest and terms, and which govern in the event of any inconsistency with this page. Submitting an inquiry does not reserve or secure an allocation.
Eligibility. Interests are expected to be available only to accredited investors. Investor access is limited to eligible investors and subject to applicable securities laws, jurisdictional requirements and opportunity-specific eligibility criteria. The specific securities exemption relied upon, and any related verification requirements, will be stated in the offering documents.
Targets and illustrations. Target net IRR, target multiple, horizons and the illustrative cash flow are objectives and hypothetical examples based on assumptions that may not be realised. They are not forecasts, projections or guarantees of future performance. Actual results will differ, possibly materially.
Risk of loss and illiquidity. An investment in the Fund is speculative, illiquid and involves a high degree of risk, including loss of the entire investment. There is no public market for Fund interests and transfer is restricted. The Fund has no operating or performance history. Past experience of the Manager's principals and the operating traction of portfolio companies are not indicative of future Fund results; increases in a portfolio company's valuation are not realised investor returns.
Fees and conflicts. The Manager charges a 2% annual management fee on assets under management and the General Partner is entitled to carried interest on profits, each as defined in the Fund documents, together with Fund expenses. The Fund invests in companies founded, owned or operated by the Manager's principals, which creates conflicts of interest; related-party valuation and approval procedures are described in the PPM. Prospective investors should consult their own legal, tax and financial advisers.